Your step-by-step selling guide, transparent cost calculator and timeline—all in one place.
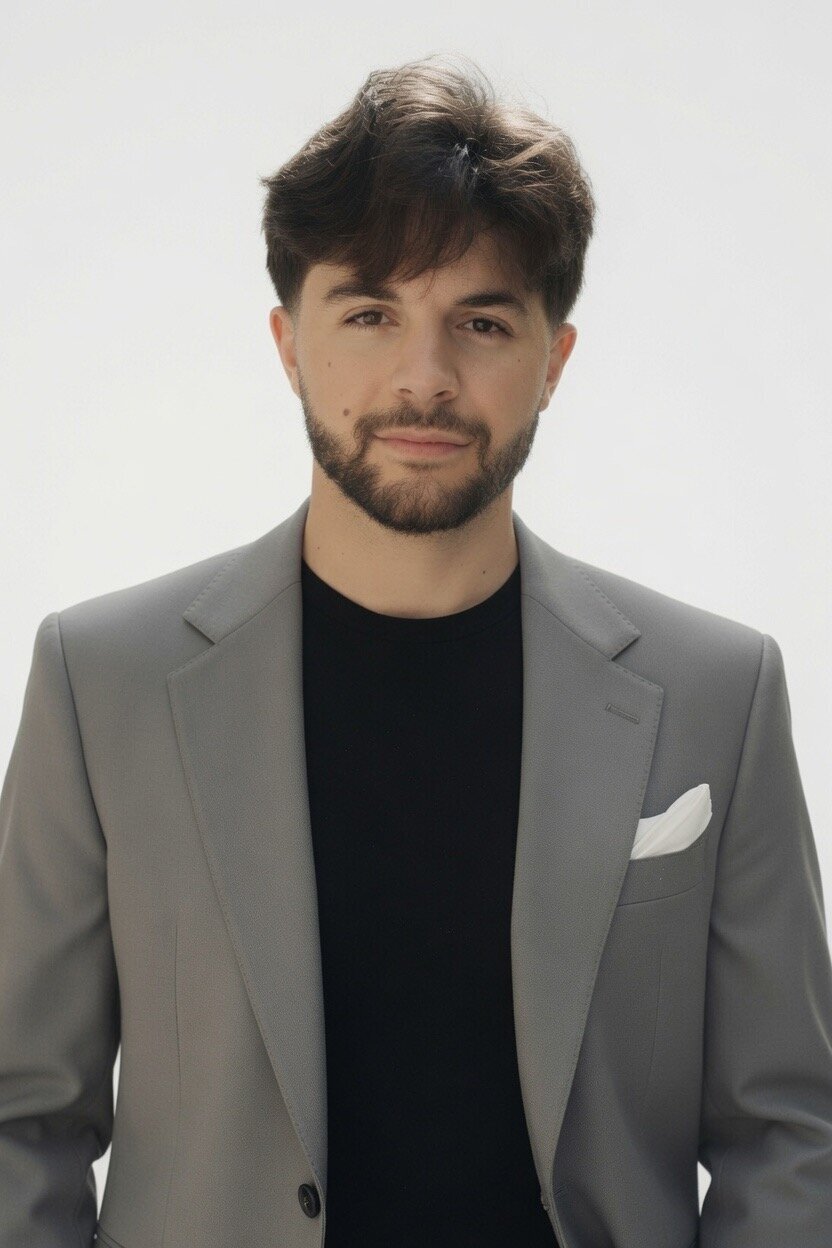
Alexandre “Alex” GirouxNYS Licensed Real Estate Salesperson607-793-9270 · Alex@HartandHomes.com
Your home deserves a story of its own. I bring five years of real estate photography, video, and marketing experience through alexgfilm to the way we plan your sale.
Click a step or use Next to walk through your sale. This is a suggested schedule; Alex and your lawyer will help set dates for your home.
Step 1 of 74–6+ weeks before your home goes on sale
Start with a home inspection.
“I always recommend a pre-listing inspection.” — Alex
This general inspection is usually optional; Alex recommends it. An inspector checks the home for problems and gives you a written report. Do this before picking repairs or taking listing photos. Ask for a price before booking. Choose a lawyer early, too. Your lawyer explains the sale papers and what you must tell buyers about the home. The buyer may still order their own inspection.
Suggested inspection budget: $700. Get a quote before booking.
1 / 7
Some homes need more time. This timeline does not predict how quickly a home will sell.
A good first conversation makes the numbers clearer. Explore banks and credit unions in and around Tompkins, Cayuga, Cortland, Tioga, Chemung, Schuyler and Seneca counties, then compare a few written offers.
Your local lender directory
21 options
Includes local institutions and regional or national banks serving the area. This is a starting directory, not an exhaustive list or a ranking. Confirm lending coverage for the property’s address; credit unions require membership.
Tompkins Bank & TrustBank
Fixed-rate and adjustable-rate mortgages; HomeOne and Home Possible options; construction, land and renovation financing. Also lists green-home, seasonal-home and no-closing-cost programs. Ask which fit your purchase.
Fixed-rate and adjustable-rate mortgages, first-time buyer programs and refinancing. Ask about membership, down-payment options and available help with your first purchase.
Beginnings Credit UnionCredit union · formerly CFCU
Fixed-rate and adjustable-rate mortgages; FHA, VA and USDA options; jumbo, land and construction loans. Also lists medical-professional and community-hero options. Ask about eligibility and the conditions on no-closing-cost loans.
Home purchase loans, homebuyer education, and Homebuyer Dream Program assistance for eligible buyers. Ask about income requirements and available assistance funding.
Fixed-rate mortgages, construction and land financing, and financing for qualifying manufactured homes. Homebuyer Dream Program assistance may be available to eligible buyers.
Home purchase and refinance mortgages, with online tools and home-lending support. Ask which programs and assistance options are available for your property and situation.
Purchase and refinance mortgages, construction financing, and first-time buyer options, including a no-closing-cost first-time buyer program. Ask which costs are covered and what conditions apply.
Home purchase and refinance mortgages, plus home equity lines of credit for existing homeowners. Ask for a comparison of purchase-loan options and the cash you would need at closing.
Conventional, VA, construction and renovation mortgages, plus land, manufactured-home and portfolio lending options. Also lists no-closing-cost and lower-mortgage-insurance options; availability varies by location.
Conventional fixed-rate, adjustable-rate, low-down-payment and jumbo mortgages, plus lot and construction loans. Ask about membership and financing for your specific property.
ESL Federal Credit UnionCredit union · includes former Generations Bank
Fixed-rate and adjustable-rate mortgages, FHA and Home Possible options, and investment-property financing. Ask about membership and affordable-homebuyer programs. ESL completed its acquisition of Generations Bank in January 2026.
Fixed-rate and adjustable-rate mortgages, plus home equity financing for existing owners. Ask about membership, purchase-loan terms and first-home financing options.
Mortgage lending through a locally owned bank serving Tompkins and Cortland counties, with offices in Dryden, Cortland and Homer. Contact its lending team for current loan types, terms and down-payment requirements.
Fixed-rate, adjustable-rate and jumbo mortgage options. Ask the New York bank’s mortgage team about purchase financing and programs for your property location.
Home purchase and refinance lending with mortgage loan officers and homebuyer resources. Ask which loan and assistance programs apply to your income, property and down payment.
Mortgage financing for buying, building and refinancing, with local mortgage specialists and low-down-payment options. Ask about first-time buyer eligibility and total closing costs.
Home purchase mortgages, preapproval and refinancing, with online applications and mortgage specialists. Ask for a personalized comparison of loan programs and costs.
Purchase, refinance, construction and renovation financing. Its loan programs include conventional fixed and adjustable rates, jumbo, FHA and first-time buyer options. Ask about property-type requirements and assistance.
Residential mortgage lending through a community bank in the northern Finger Lakes region. Contact the bank for current purchase-loan programs, down-payment requirements and service area.
Fixed-rate and adjustable-rate mortgages, first-time buyer programs, jumbo and construction loans. Also offers financing for land, seasonal properties and manufactured housing, plus no-closing-cost options with conditions.
Offerings checked September 7, 2026 using each institution’s linked website. Programs, rates, funding and eligibility can change. Ask the lender for current terms; this directory is not a loan approval or a promise of assistance.
You choose your lawyer. These firms say they handle home purchases or other real estate work. Call to ask if they can help with your home, your lender and your dates.
Bousquet Holstein PLLC
Ithaca / Syracuse
Helps people buy and sell homes. Handles contracts, home loans, title work and closing.
Checked September 7, 2026 on the firms’ linked websites. This list is not a ranking or every local option. Ask about fees, who will handle your purchase, and whether the firm can take you as a client.
Start with the sale price. Subtract what you owe and what it costs to sell. We have filled in example budgets for common costs. Change them to match your quotes. These are planning examples, not local price quotes.
New to selling? Start with these basics
The sale price is not all yours to keep. Part may pay off your home loan and cover the cost of selling.
You do not usually write a separate check for every cost. Loan payoff and many sale fees are paid from the sale money at closing. Inspections, cleaning and repairs are often paid earlier. Ask each person when their bill is due.
The big number is for the whole sale. We also subtract preparation and moving costs, even if you pay them separately. This helps you plan what is left after the move.
Do not know an amount? Leave the example while planning, then ask for a quote. Enter 0 only when the cost does not apply. A blank counts as 0 and can make the result look too high.
Step 1 of 4 · Home
1 Start with your home
Use a price you want to explore. Alex can help you choose a realistic estimate.
Your mortgage is your home loan. Ask the lender for a payoff quote: the full amount needed to clear it on a certain date, including interest and fees. Enter 0 if you have no loan.
2 Add your agent fees
Both fields start at 3% as examples, for a combined 6%. Fees are negotiable. Change these to the fees in your agreement.
This pays the agent helping you sell. A percent is a share of the sale price. At 3%, a $300,000 sale has a $9,000 fee. Use your agreed rate.
The buyer may have their own agent. This is the share you agree to pay that agent, if any. It is separate from your agent’s fee. Enter 0 if you are not paying it.
3 Add the other main costs
Example budget: $1,500. Your lawyer explains the legal papers and helps finish the sale. Ask for a written fee and when it is due. Check which other fees it includes.
Example budget: $700. An inspector checks the home and gives you a report before it goes on sale. I recommend this optional check. Ask the inspector for the price and when to pay. Enter 0 if you choose not to order it.
Example budget: $1,500. Money for movers, storage or a short stay between homes. Ask for quotes and confirm your move-out date before booking.
NY transfer tax: calculated from your priceThis is a tax on the property sale. We include a basic estimate automatically.
Example budgets for cleaning, property records and filing fees are included below. Open these sections to review them and add any other costs.
More work before the sale
Some checks are optional; local rules or your contract may require others. Ask your local office and lawyer what applies before booking radon, water, septic or pest tests.
Money for repairs you choose to make. Ask a contractor for a written price before work starts. Usually paid before the sale is finished.
Example budget: $400. Cleaning, clearing out clutter and tidying the yard.
Interest, power, insurance and upkeep. Do not count the loan balance again.
More costs when the sale is finished
A second mortgage, home-equity loan or other debt that must be paid from the sale.
Example budget: $400. Title means the record of who owns the home. A survey shows property lines. Ask your lawyer which checks you pay for and whether their fee already includes them.
Example budget: $150. Money to file official papers or handle the closing. Ask your lawyer for your share. Do not add it again if included in another fee.
Sometimes a buyer asks you to pay some of their costs instead of lowering the price. Enter only what you agree to pay. Do not count the agent fees twice.
You and the buyer may split bills based on how long each owned the home. Your lawyer works out what you still owe when the sale finishes.
Some condos and neighborhoods have a group that collects dues. Ask that group about fees for selling or bills you still owe. Use 0 if none apply.
A service plan that may cover certain repairs for the buyer, subject to its rules. Enter a cost only if you agree to buy one.
Any cost not counted elsewhere. Use this for a flat agent fee instead of entering a percentage above.
A credit is money added back to your side of the closing bill, such as the buyer’s share of taxes you paid early. Ask your lawyer for the amount. The buyer’s earnest money deposit is already part of the sale price; do not add it here.
Tax details — only if they apply
Leave blank to use the automatic estimate. Enter your lawyer’s figure, or 0 if they confirm you do not owe it.
Use a tax professional’s estimate. This calculator does not work out tax on your profit.
For an ordinary full-property sale in the Finger Lakes, outside NYC. The automatic NYS base transfer tax is $2 per $500 or part of $500 when the sale is over $500. Other taxes or special rules may apply; ask your lawyer. Add extra amounts under other sale costs. NYS tax source.